August marked a broad seasonal cooling across the Bay Area. Closings declined year over year in 13 of 14 counties and month over month in 12, while months of supply increased from July in 13 counties. The shift reflects the typical late-summer slowdown as the market transitions from the spring/summer peak toward the fall market peak.
Competition remained stronger than a year ago. The share of sales closing above list increased year over year in all 14 counties, while average days on market improved in 11. Price reductions increased in 10 counties, consistent with the seasonal rise in listing adjustments as the market moves toward fall and winter.
Single-family homes continued to show stronger market conditions than condos. Single-family closings fell year over year in nine counties but increased in five, and days on market declined in 13. The share of sales closing above list increased across every county. By contrast, condo price reductions increased in 12 counties, while condo days on market rose in six — signaling a more uneven recovery.
Condo momentum appears to be moderating after a strong summer. The condo median increased year over year in six counties and declined in eight, while the share of condos selling above list rose in only eight. August is the first month of data following new condo lending regulations, so it is too early to determine whether the slowdown reflects the regulations or the normal late-summer seasonal pattern.
San Francisco remains the regional standout. Condo sales increased 11% year over year to 214, the condo median rose 22% to
$1.23 million, and active condo listings fell 36%. San Francisco was the only county where condos showed both meaningful price and closed transaction growth.
September watch: The strongest appreciation outside San Francisco was concentrated north of the city, with Marin posting the region’s second-highest year-over-year gain. Condo sales and pricing will be closely watched to determine whether August’s slowdown is temporary or the beginning of a broader shift. The performance of smaller versus larger condo buildings will also be important, particularly as the impact of the new lending regulations becomes clearer. Atherton’s nearly $10 million increase in its median price, driven by a few high-value sales, will be another notable test of whether recent gains will be sustained.
Report created in good faith using public and proprietary data from sources deemed reliable but may contain errors and is subject to revision. Data is pulled at the end of the month, and last-period figures may still be preliminary due to late-reported activity. All numbers are approximate and may change, including Private Exclusive sales and other transactions not publicly reported at the time of publication.
How to Read This Report: County and Submarket Guidance
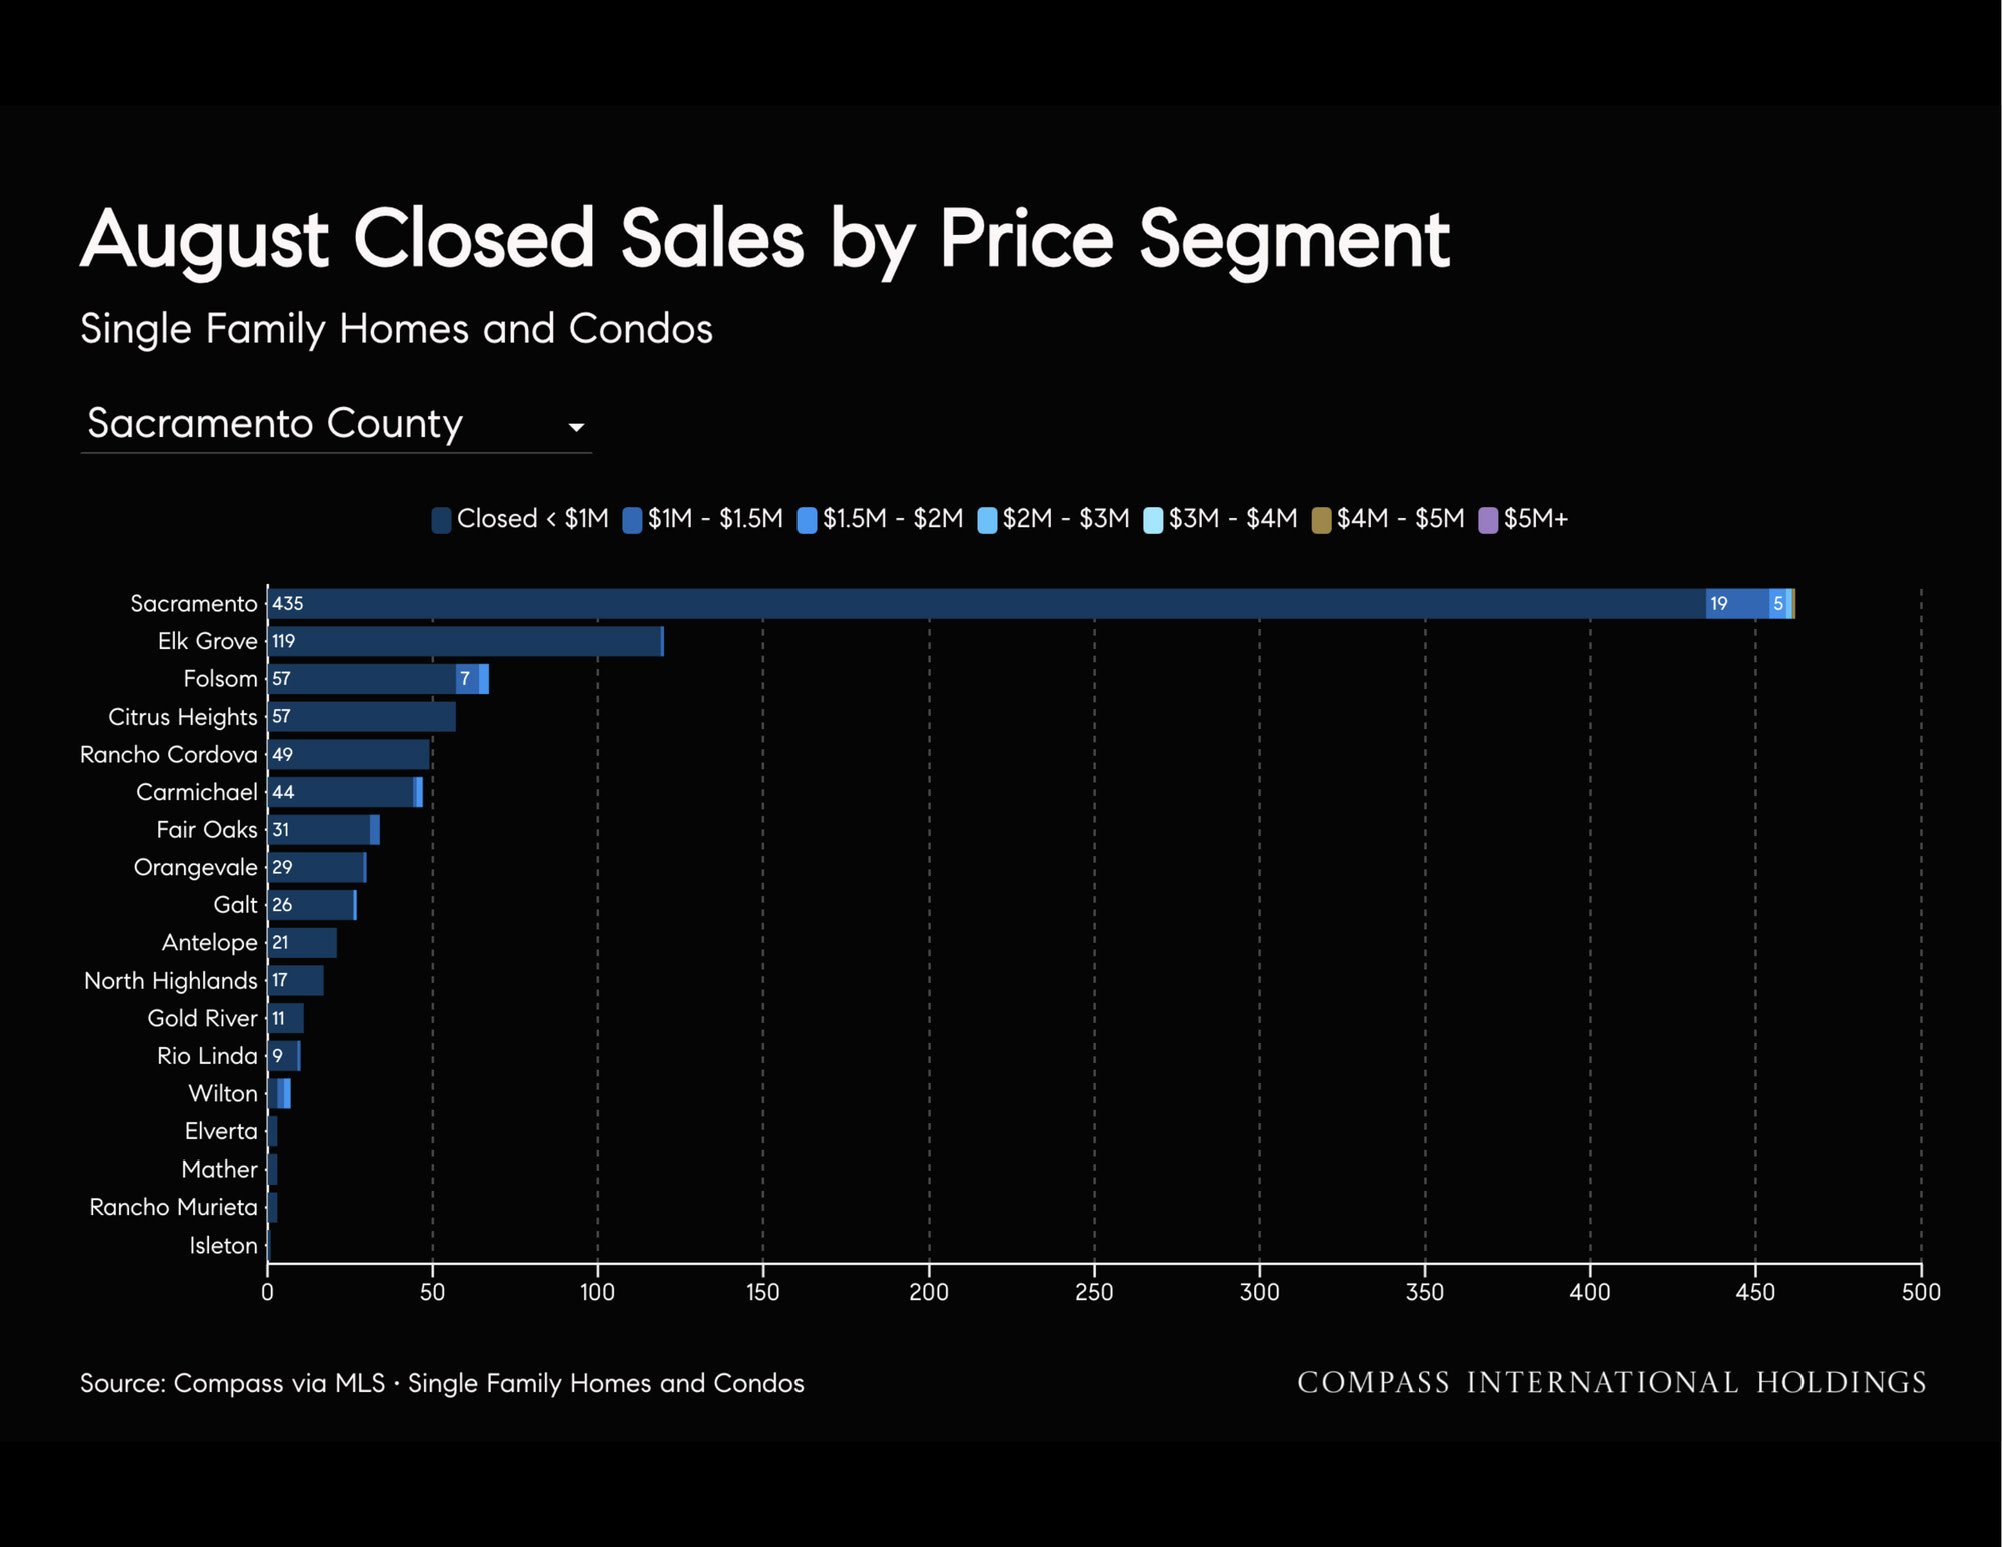
Data quality: Sacramento is the report's largest inland market: 894 single-family and 49 condo closings in August. Single-family data are robust and reliable. Condo data (49 sales) are solid for county-level trend analysis.
Single-family softening: Single-family sales fell 8% YoY, a moderate decline, but the headline is inventory and supply metrics. Contracts increased 6%, suggesting stabilizing demand, but closings declined, indicating a sales-supply timing lag. Months of supply rose from 2.5 to 2.7, while absorption improved 3 points to 44%.
What's unusual: Despite softening conditions, 35% of sales closed above list, up 7 points YoY—Sacramento is moving counter to other inland markets, showing maintained competition even as supply rises.
Price stability: The median held essentially flat at $549,950, suggesting the slowdown is tempo-driven, not value-driven. The 17% increase in price reductions (to 994) and 38% reduction rate indicate pricing pressure nonetheless.
Condo collapse: Sacramento's condo market fell 42% YoY (49 vs 84 closings)—the steepest decline in the region. The condo median fell 18% to $265K, the largest price drop in the region. Months of supply doubled from 3.1 to 6.3, a massive expansion indicating weakening condo demand.
Inland characteristics: Sacramento lacks Bay Area commute premiums and is most sensitive to employment, new construction, and affordability constraints.
Guidance: Sacramento's single-family market is gradually loosening as sales decline and supply increases, but price resilience and overbid strength suggest the market has not collapsed. The condo market deterioration is severe and is the report's most cautionary condo indicator. Treat condo data as a warning signal of potential multi-unit building softening across the region.
Sacramento Market Recap
Sales: 894 single-family homes closed, down 8% YoY and 12% from July. Condo closings fell 42% YoY to 49, the steepest condo decline among the counties.
Prices: The single-family median was essentially unchanged at $549,950, with price per square foot also flat at $333. The condo median fell 18% to $265,000.
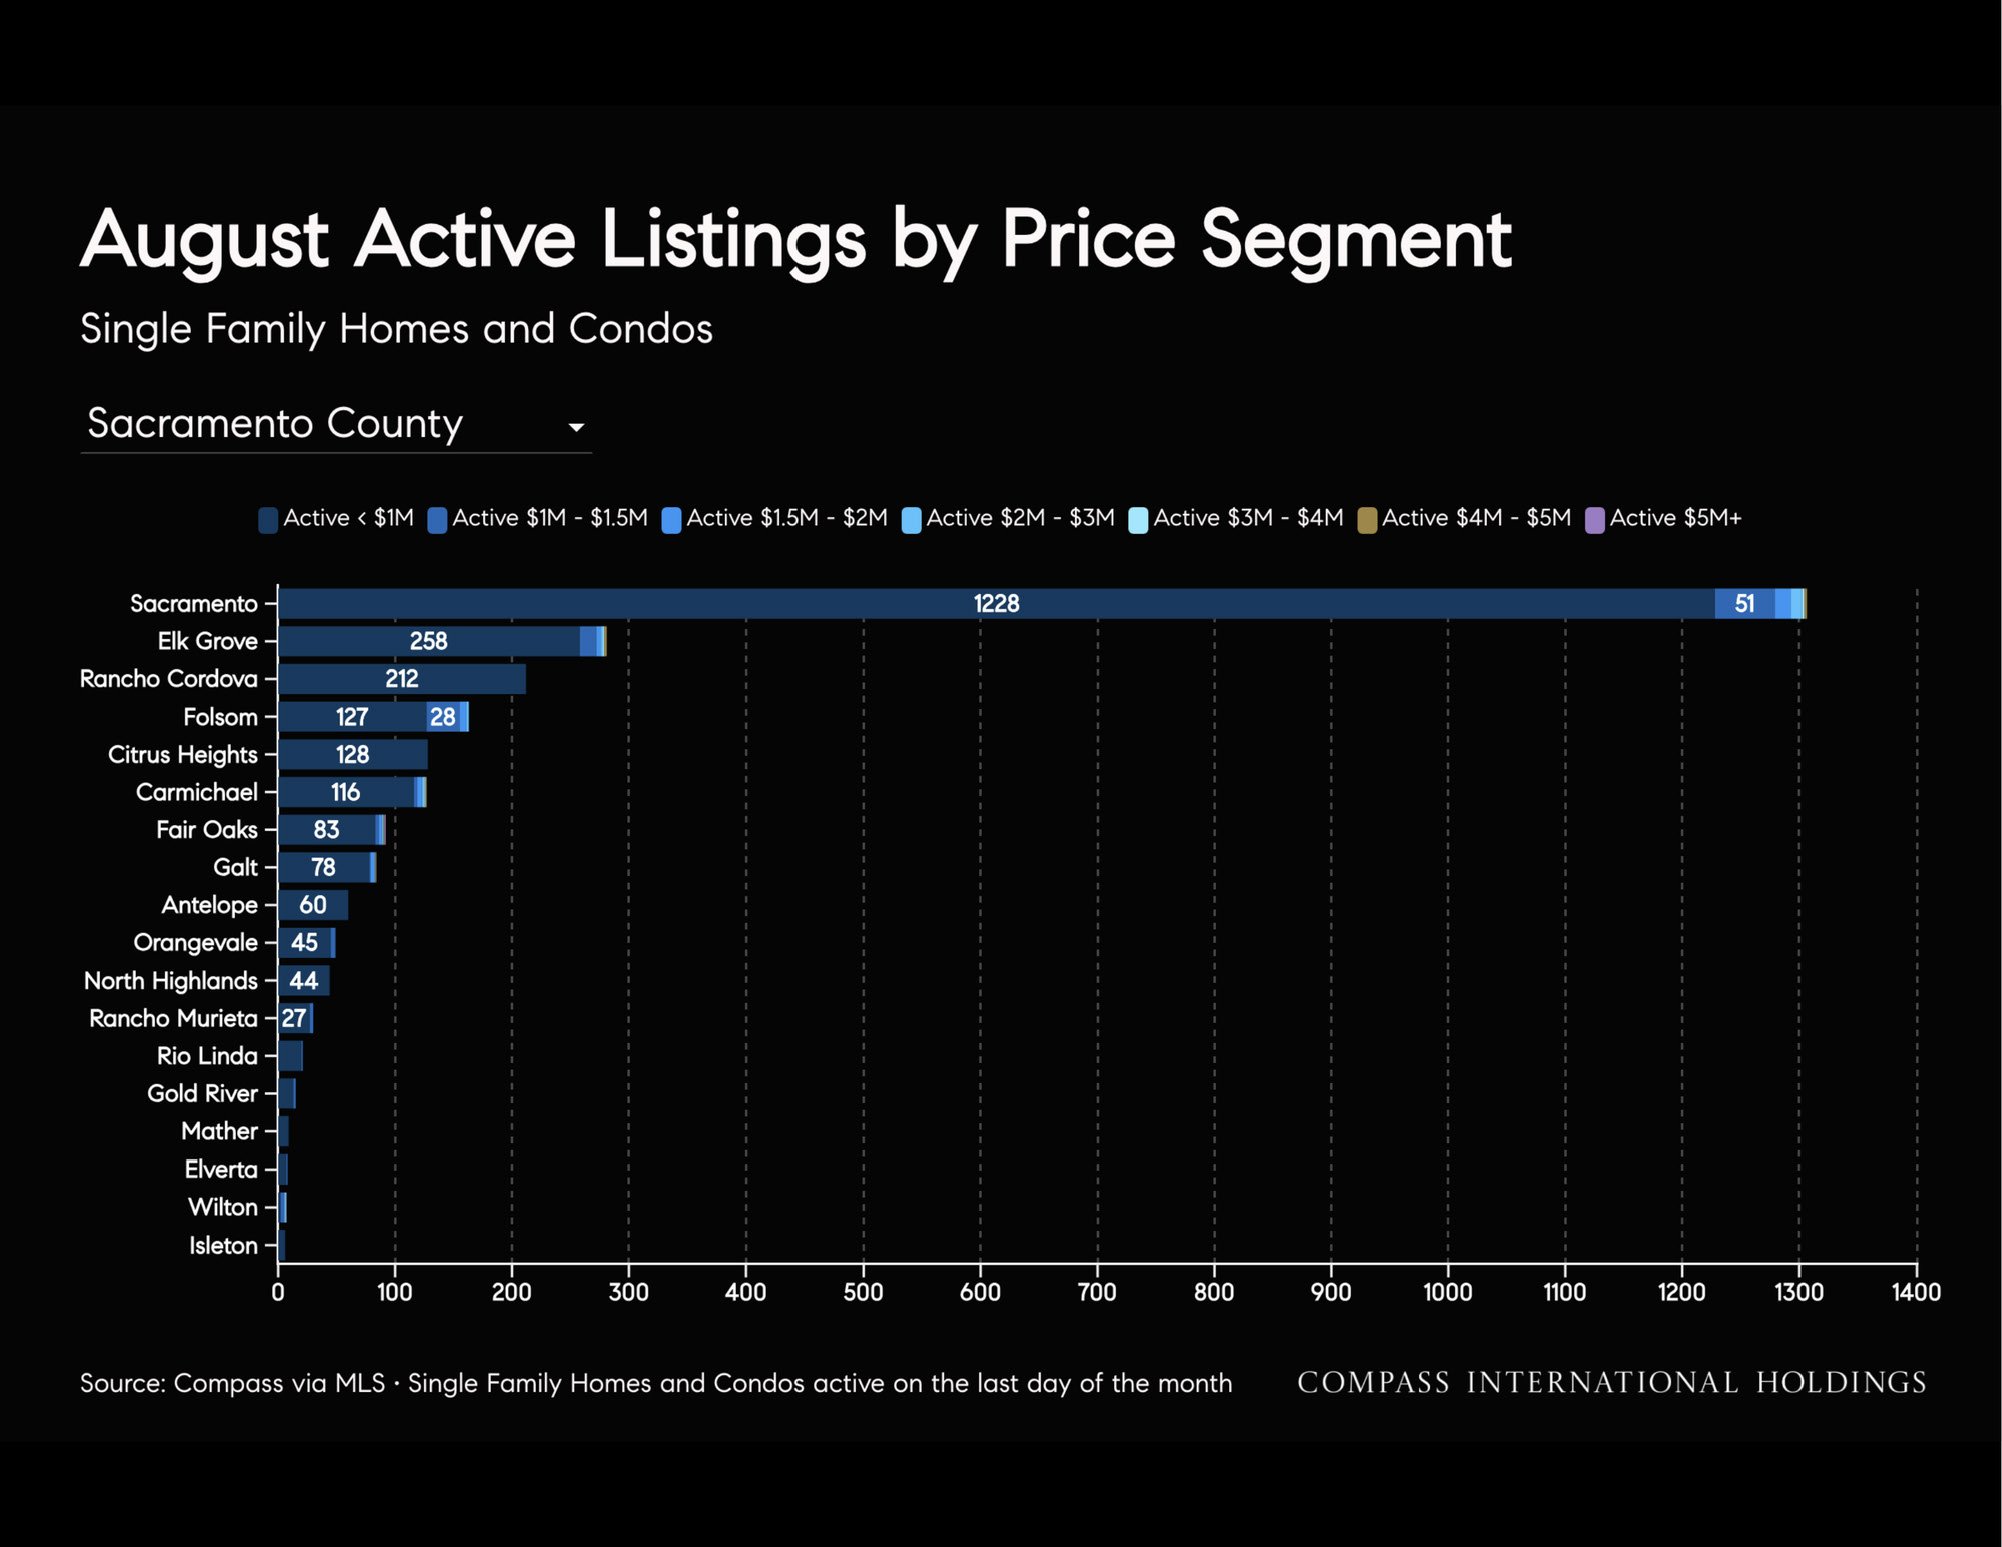
Inventory: Combined active listings increased 1% YoY to 2,718, driven entirely by condos. Single-family actives fell 1%, while condo actives increased 17%.
Single family: Contracts increased 6% and absorption improved 3 points to 44%, but closings declined 8% and months of supply rose from 2.5 to 2.7.
Negotiation: Single-family price reductions increased 17% to 994, with the reduction rate rising to 38%. At the same time, 35% of sales closed above list, up 7 points YoY.
Condos: The condo market weakened considerably. Contracts fell 29%, absorption dropped 14 points to 22%, and months of supply doubled from 3.1 to 6.3. Price reductions increased 39%. MoM: Single-family closings fell 12%, days on market increased from 37 to 40, and months of supply rose from 2.4 to 2.7. Condo months of supply increased from 5.3 to 6.3.
Bottom line: Sacramento's single-family market is relatively stable on pricing but gradually loosening as sales decline and supply increases. The condo market is significantly weaker, with sharply lower sales, falling prices, and substantially more available inventory.

Single Family Homes




Condos


All Homes


Macroeconomic and Demographic Data
Mortgage rates remain stubbornly elevated at 6.8%, near a 15-month high, as government spending, geopolitical tension, and inflation fears keep bond markets on edge. Don't expect meaningful rate relief soon. Inflation, while easing for two straight months, is still running well above the Fed's 2% target. Locally, the story has flipped. Ater years of Bay Area inflation running below the national rate, home price appreciation has resumed.
The labor market sends mixed signals. Nationally, August jobs data showed surprising strength, averaging 80,000 new jobs a month in 2026. That’s good for homebuyer confidence, but also fuel for inflation and higher-for-longer rates. Locally, it's the opposite: the Bay Area has shed jobs five months running, and tech employment keeps contracting nationally. Low hiring rates continue to suppress relocation-driven demand, a key historical driver of home sales.
The bright spots: foreclosures remain near historic lows thanks to high homeowner equity, and Bay Area home prices are outperforming, up 3.3% year-over-year versus 1.5% nationally. Millennials (30-39) now account for the largest share of mortgage borrowers. Perhaps most notably for our market, inbound migration to the Bay Area has turned positive for the first time in years, with Seattle, Austin, and Manhattan feeding new arrivals.


